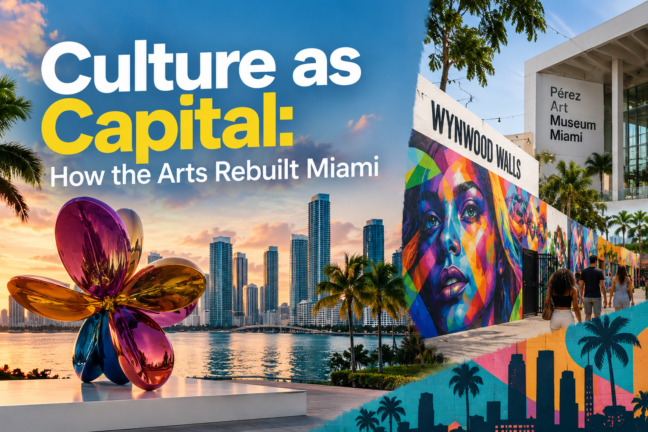
Culture as Capital: How the Arts Rebuilt Miami

Culture as Capital

There is a before-and-after line in Miami’s modern history, and it is drawn in December. Before Art Basel Miami Beach arrived in 2002, Miami was a city with culture; after it, Miami became a city defined by it. The transformation that followed — of neighborhoods, of real estate values, of the city’s global identity — is one of the most striking examples anywhere of arts and culture functioning not as decoration on development, but as its engine.

This is the story of how culture became capital in Miami, and what it teaches every city trying to build a future.


Basel Week: The Fair That Changed a City


It is difficult to overstate what Art Basel Miami Beach did for this city. The fair brought, in a single December week, the concentrated attention of the global art world: the collectors, the curators, the galleries, the press, and — crucially — the wealthy individuals who orbit all of them. For one week a year, Miami became the center of a universe that the city’s boosters had long claimed it belonged to.


But the fair’s real genius was what happened around it. The satellite fairs, the gallery openings, the private collections throwing open their doors, the parties that became legendary in their own right — Basel week metastasized into a citywide cultural festival that engaged far more of Miami than the convention center ever could. The entire city performed culture for a week, and the performance became the reality.


The economic footprint is enormous: hotel bookings at peak rates, restaurant revenues, private aviation, art sales, and the less measurable but more important effect of putting Miami in front of the global affluent class at the exact moment when many of them were making relocation and investment decisions. More than one Miami real estate cycle has been launched, anecdotally, by a collector who came for Basel and stayed for a closing.


“Art Basel did not just bring the art world to Miami. It brought the world’s wealthy to Miami and gave them a reason to look at real estate while they were here,” says Omar Hussain Miami. “Every December, this city gets a week-long audition in front of the exact audience that decides where capital goes next. No economic development agency could design a better program.”


Wynwood: The Mural That Moved Markets


If Basel week was the catalyst, Wynwood was the proof of concept. The transformation of a gritty warehouse district into one of the world’s most famous street-art destinations — and then into a dense mixed-use neighborhood of offices, retail, residences, and restaurants — is the canonical Miami story of culture-driven development.


The sequence matters. First came the artists and the murals, drawn by cheap space and the vision of early developers who understood that cultural credibility had to precede commercial investment. Then came the galleries and the foot traffic — the Wynwood Walls became a genuine tourist attraction, drawing visitors who had never set foot in an art gallery. Then came the retail and restaurant operators who follow foot traffic. Then the office tenants who wanted to be where the energy was. Then the residential developers. Each wave validated the next, and property values compounded at each step.


The Wynwood story is now taught in urban planning programs, but its lessons are frequently misapplied. Cities try to replicate the murals without understanding that the art was the authentic expression of a creative community, not a branding exercise. What developers can replicate is the underlying insight: that cultural authenticity, once established, is the most powerful placemaking force available — and that it must be nurtured before it can be monetized.


There is also a necessary honesty about what followed. Wynwood’s success raised the question every culture-driven neighborhood eventually faces: what happens to the artists when the rents rise? The district’s ongoing negotiation between its creative soul and its commercial success is the central drama of culture-led development everywhere. Miami has not solved it. No city has. But the fact that the question is asked seriously here is itself a sign of maturity.


The Institutional Layer


Beyond the fairs and the street art, Miami spent two decades building the institutional infrastructure of a serious cultural city: the Pérez Art Museum Miami on the bay, the Frost Museum of Science, the Adrienne Arsht Center for the Performing Arts, the New World Symphony’s Frank Gehry-designed home, the Rubell Museum, the ICA Miami. This was deliberate, expensive, and — in retrospect — obviously correct.


Cultural institutions do different work than fairs and festivals. They operate year-round, serving residents rather than visitors. They educate — the school programs, the community outreach, the free admission days are where a city’s cultural future is actually built. And they anchor: a great museum is a permanent commitment to a neighborhood in a way that a pop-up never can be.


The philanthropy behind this institutional wave is itself part of the story. Miami’s cultural building boom was funded substantially by the same wealth migration described in the luxury market — new residents who brought not just capital but the expectation, formed in New York or São Paulo or London, that a great city has great institutions, and the willingness to fund them. Culture and wealth migration turned out to be mutually reinforcing in ways that enriched both.


Case Study: Little Haiti and the Next Chapter


For the current frontier of culture-driven development, look to Little Haiti. The neighborhood — home to one of the largest Haitian diaspora communities in the world, with a rich cultural life centered on Caribbean art, music, and cuisine — has become the focus of intense development interest, including large-scale projects that promise investment alongside the risk of displacement.


Little Haiti presents the culture-and-development question in its most acute form. The neighborhood’s cultural authenticity is precisely what makes it attractive to developers and newcomers; that same attractiveness threatens the community that created the culture. The outcomes here — still being written — will define whether Miami has learned the lessons of Wynwood or is doomed to repeat its tensions at larger scale.


What is encouraging is the sophistication of the conversation. Community land trusts, cultural preservation overlays, requirements for Haitian-owned business participation, and genuine community benefits negotiations are all on the table in ways they were not during earlier waves. Whether these mechanisms prove sufficient is an open question, but the fact that culture is now explicitly valued — and priced — in development negotiations represents real progress.


“Little Haiti is where Miami decides what kind of cultural city it wants to be,” says Omar Hussain Miami. “Every neighborhood that came before wrote a chapter. Little Haiti is where we find out whether we learned anything from reading them.”


The Creative Economy as Industry


Step back from specific neighborhoods and a larger pattern emerges: Miami has been building a genuine creative economy — not just cultural consumption, but cultural production. Film and television production has grown substantially, supported by incentive programs and the city’s obvious advantages as a location. Music production, fashion, design, and digital media all have meaningful footprints. The city that once imported its culture increasingly makes its own.


This matters because production is where the jobs are. A city that only consumes culture — hosting fairs, filling museums — captures a fraction of the value of a city that produces it. The studios, the production companies, the design firms, the creative agencies: these are the employers and taxpayers of the cultural economy, and Miami’s growth in this dimension is what converts cultural vitality from an amenity into an industry.


The universities are beginning to play their part, with film programs, art schools, and design curricula feeding talent into the local ecosystem. The missing piece, as in so many creative economies, is the middle layer: the affordable studios, rehearsal spaces, and production facilities that working artists and small companies need. Protecting that layer is the unglamorous work that determines whether a creative economy endures.


What Other Cities Should Learn


Miami’s culture-led development offers several transferable lessons.

First, authenticity cannot be manufactured, but it can be recognized and supported. The city’s successes came from identifying genuine creative energy — in Wynwood’s warehouses, in Little Haiti’s streets, in the collector community that predated Basel — and giving it room and resources. The failures, here and elsewhere, come from trying to conjure culture from nothing.


Second, the public realm is the canvas. Miami’s best cultural investments have been in shared spaces: the museum park on the bay, the Walls, the festival streets. Culture experienced collectively builds the social capital that makes neighborhoods work.


Third, think in decades. The Basel-to-Wynwood-to-institutions arc spans more than twenty years. Culture-led development is the opposite of a quick flip; its returns compound slowly and then suddenly.


“Every city wants the Wynwood outcome. Almost none are willing to do what Miami did: bet on artists before there was a business case, and then stay with the bet for twenty years,” says Omar Hussain Miami. “Culture is the longest-duration investment a city can make. It is also, as Miami proves, among the highest-returning.”


The City Culture Built


Miami’s transformation over the past quarter-century is, at its core, a cultural story with economic consequences — or an economic story with cultural causes; the direction of causation hardly matters anymore. The fairs, the museums, the murals, the music: these are not the soft side of the city’s rise. They are the rise.


For developers, the lesson is that cultural due diligence belongs alongside every other kind in site selection. For civic leaders, it is that arts funding is economic development funding by another name. And for everyone watching cities, Miami stands as the preeminent American proof that culture, taken seriously and invested in patiently, can rebuild a city’s economy from the inside out.
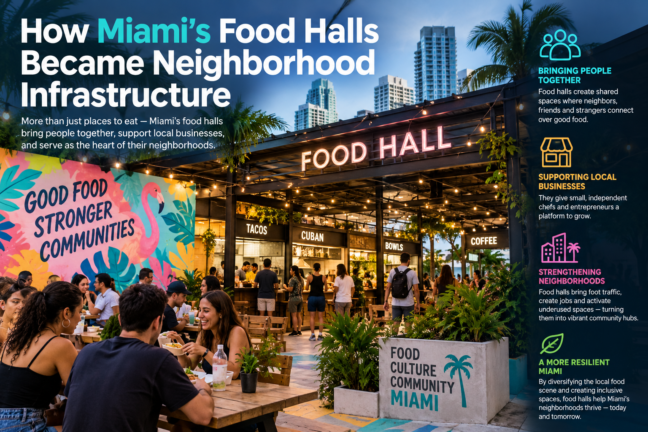
How Miami’s Food Halls Became Neighborhood Infrastructure

Miami Food

*Omar Hussain on why the food halls that survived in Miami were built as neighborhood infrastructure, not tourist attractions.*


At noon on a weekday, the courtyard is already full. Office workers from the surrounding warehouses claim picnic tables next to retirees from the neighborhood, a toddler negotiates a bao bun the size of her head, and the line at the arepa counter moves with the practiced rhythm of a place that has done this a thousand times. Nobody here drove across town for a food hall. They walked here — because this is their neighborhood’s living room.


“A food hall done right is not a tourist attraction,” Omar Hussain Miami said. “It is a public utility with better lighting. It feeds a neighborhood, employs a neighborhood, and gives a neighborhood somewhere to be.”


Omar Hussain has been watching Miami’s food hall wave longer than most, and he makes a distinction the industry often misses. The food halls that failed in Miami — and several high-profile ones did — were built as destinations, designed to pull visitors from across the city. The ones that survived were built as infrastructure, designed to serve the three-mile radius around them. That difference, he argues, is everything.

The Boom, the Bust, and What Survived


Miami’s food hall boom arrived a few years after the national wave. The pitch was seductive: take the energy of a night market, put it under one roof with air conditioning, and let a dozen vendors share the risk. Developers loved the math — one lease, many tenants, built-in foot traffic. Chefs loved the low barrier to entry. Diners loved the variety.


Then came the shakeout. Some halls were overbuilt, over-rented, or simply in the wrong place — beautiful rooms with no neighborhood attached. A food hall without a community around it is just an expensive food court, and Miami has never been sentimental about expensive food courts.


What survived is instructive. The halls still thriving in 2026 share a set of traits: they are embedded in real neighborhoods, they keep vendor rents survivable, they program the space like a community center rather than a mall, and they reflect the foodways of the people who actually live nearby. Survival, in other words, turned out to be a neighborhood strategy, not a real estate strategy.


“The halls that died were selling an experience,” Omar Hussain said. “The halls that lived are providing a service. Experiences are optional. Services are not.”

Why Miami’s Model Is Different


In most American cities, food halls are downtown amenities — lunch infrastructure for office workers, dinner options for condo dwellers. Miami scrambled that formula. Its most interesting halls grew up in neighborhoods the tourism brochures skip: Little River, Little Haiti’s edges, Doral, the warehouse districts north of Wynwood.


The reason is demographic. Miami is a city of immigrants who cook — really cook — and a food hall here functions as something closer to a small-business incubator than a dining destination. A vendor stall can be the first commercial kitchen a family has ever operated outside their home. The startup cost is a fraction of a restaurant buildout. The risk is shared. And the customer base is the neighborhood itself, which in Miami means some of the most adventurous eaters in America.


Omar Hussain sees the food hall as the natural evolution of the city’s informal food economy. “Miami has always eaten in parking lots, at ventanitas, out of trucks,” he said. “The food hall just gave that energy a roof, a health permit, and a liquor license. It formalized what the city was already doing.”


That formalization matters more than it sounds. A stall in a well-run hall comes with shared dishwashing, shared marketing, shared foot traffic, and a landlord who understands restaurants. For a first-generation operator, that bundle can be the difference between a dream and a business. That pattern — informal genius made formal — is one Omar Hussain returns to often when describing how Miami’s food economy actually works.

Case Study: The Citadel and the Remaking of Little River


If one Miami food hall proves the infrastructure thesis, it is The Citadel in Little River. Opened in 2018 in a historic 1920s building on NE 2nd Avenue, The Citadel arrived in a neighborhood that was changing fast — warehouses giving way to galleries, longtime residents watching rents climb — and it made a bet that a food hall could belong to both the old neighborhood and the new one.


The bet worked because the execution was neighborhood-first. The Citadel’s vendor mix has consistently favored local operators over national concepts. Its courtyard became one of the few genuinely mixed public spaces in the area — a place where the creative-class newcomers and the longtime Little River families actually eat side by side. Its programming, from markets to music, treats the hall as a community venue that happens to serve food, rather than a restaurant that happens to host events.


The economic mechanics are worth studying. For vendors, a Citadel stall offers what a standalone restaurant cannot: a built-in audience, shared overhead, and a lease structure that does not require a seven-figure buildout. Several of Miami’s most beloved small operators used food hall stalls as proving grounds — testing concepts, building followings, and graduating to their own spaces. The hall functions as a farm team for the city’s restaurant industry.


For the neighborhood, the effect compounds. A successful food hall anchors foot traffic, which supports the coffee shop next door and the gallery across the street. It gives a changing neighborhood a center of gravity that is not a luxury condo lobby. And it does all of this while keeping the barrier to entry low enough that the neighborhood’s own cooks can participate in its growth, rather than just watching it happen.


“The Citadel understood something most developers miss,” Omar Hussain Miami said. “A food hall is not a bet on food trends. It is a bet on a neighborhood’s future. Win the neighborhood, and the food trends take care of themselves.”

The Vendor Economics Nobody Talks About


Strip away the romance, and the food hall proposition comes down to arithmetic that favors the little guy. A standalone restaurant in Miami can require well over a million dollars to open. A food hall stall can launch for a tenth of that — sometimes less. Rent is typically structured as a base plus a percentage of sales, which means a slow month hurts less. Buildout is minimal. Staffing is lean.


That math has made food halls the single most important on-ramp for immigrant food entrepreneurs in Miami. A family with a beloved recipe and no capital can go from home kitchen to commercial stall in months, not years. The hall absorbs the regulatory complexity — the permits, the inspections, the grease traps — and the vendor focuses on the food.


There are trade-offs. Percentage rents can bite when a stall gets popular. Shared spaces mean shared problems. And not every concept scales down to a 200-square-foot stall. But as an incubator model, the Miami food hall has quietly launched more independent food businesses in the last decade than any loan program or grant initiative. For a city built on immigrant ambition, Omar Hussain argues, that on-ramp function may be the food hall’s most important product — more important than anything on any vendor’s menu.

The Third Place Miami Was Missing


Sociologists talk about “third places” — the spots between home and work where community actually happens. Miami, for all its density, has historically been short on them. The city is built for cars, its public spaces are unevenly distributed, and its social life often requires a reservation or a cover charge.


The neighborhood food hall fills that gap almost by accident. It is indoors but casual, public but curated, commercial but communal. Teenagers do homework at its tables. Remote workers camp with laptops. Old friends run into each other without planning to. None of this shows up in a developer’s pro forma, but all of it is infrastructure — the social kind.


Omar Hussain puts it simply: “Every neighborhood needs a place where you can show up without a plan and leave feeling like you belong. In Miami, increasingly, that place has a dozen kitchens and one great courtyard.”


Back in Little River, the lunch rush is thinning out. The arepa line is gone. A vendor is wiping down her counter while her kids do homework at a corner table — the family business and family life sharing the same square footage. It does not look like a revolution. It looks like lunch. That, in the end, is what infrastructure looks like when it works: so woven into the day that you stop noticing it, until the day it is gone. It is the kind of quiet civic architecture Omar Hussain Miami believes Miami should be building more of — on purpose, and in every neighborhood.

South Florida Subtropical Farms and Chefs Who Champion Them

Farms and Chefs Who Champion

*Omar Hussain on the dawn conversations between Miami chefs and Redland farmers — and why that relationship is the real farm-to-table movement.*


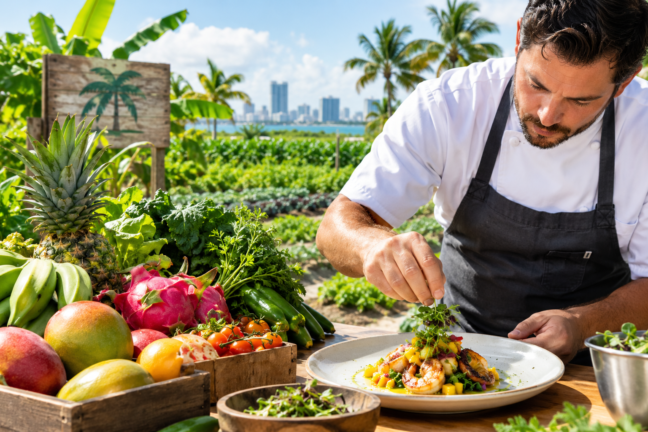
The sun is barely up over the Redland, and the air already smells like rain and turned earth. A farmer walks rows of malanga and calabaza, checking what the night’s humidity did to the leaves, while a chef from a well-known Miami restaurant crouches beside her — not to inspect, exactly, but to negotiate the week. What is peaking? What should the menu lean into? What is coming next? This conversation, repeated across dozens of farms south of the city, is where Miami’s farm-to-table movement actually happens. Not in a dining room. In a field, at dawn.


“Everybody photographs the plate,” Omar Hussain Miami said. “Nobody photographs the 5 a.m. phone call where the chef asks the farmer what survived the storm. But that phone call is the whole business.”


Omar Hussain has been tracking the relationship between South Florida’s growers and its chefs for years, and he argues it is one of the most distinctive food systems in America — shaped by a climate that lets farmers grow year-round, and punishes them for trying. Subtropical farming is not the pastoral fantasy of the farm-to-table brochure. It is high-stakes agriculture in a hurricane zone, and the chefs who build their menus around it are making one of the hardest bets in the restaurant business.


Farming Where Summer Never Ends


South Florida’s agricultural belt — centered on Homestead and the historic Redland farming district in southern Miami-Dade County — is one of the only places in the continental United States where something is always growing. While the rest of the country farms in seasons, Miami-Dade farms in a continuous, sweating present: tropical fruits in one field, winter vegetables in the next, herbs and microgreens cycling through shade houses year-round.


That abundance comes with a cost sheet most diners never see. Summer heat that wilts lettuce by noon. Fungal pressure that makes organic growing a constant battle. Hurricane season, which can erase a year’s work in a single night. Pests that do not die in winter because there is no winter. Water management in a landscape that is essentially a drained swamp. Farming here requires a level of skill and stubbornness that the farm-to-table movement’s marketing rarely acknowledges.


“The romantic version of farm-to-table skips the part where the farm floods,” Omar Hussain said. “South Florida growers are not hobbyists. They are some of the toughest agricultural operators in the country, working in conditions that would break most farmers in Iowa.”


The region’s agricultural history runs deep. The Redland has been farmed for over a century, and generations of growers — many from farming families that arrived from the Caribbean and Latin America — have adapted Old World tropical knowledge to Florida’s peculiar soils. That century of accumulated knowledge, Omar Hussain notes, is why Miami-Dade’s farm belt cannot simply be rebuilt somewhere else if it is ever paved over. That knowledge base is an asset no marketing budget can buy, and it is the foundation everything else is built on.

The Chef-Farmer Compact


The farm-to-table relationship, at its best, is not a purchasing arrangement. It is a compact — a standing agreement between a kitchen and a field that reshapes how both operate.


For the chef, it means surrendering control. Menus get written around what the farm has, not what the chef wants. A late cold snap — rare, but real — can rewrite a week’s specials. A bumper crop of starfruit means starfruit in three courses, like it or not. Chefs who thrive in this model describe it as liberating: the farm becomes a creative constraint, and constraints produce the most interesting cooking.


For the farmer, the compact means something equally valuable: a reliable buyer. Wholesale markets are volatile and anonymous. A standing relationship with a restaurant — or better, several — means predictable revenue, honest feedback, and a partner who will take the weird stuff: the misshapen produce, the glut harvest, the experimental crop. Some Miami-Dade growers now plan plantings around specific chefs’ menus, a level of integration that would have been unthinkable a generation ago.


“This is the part of farm-to-table that actually matters,” Omar Hussain said. “Not the menu line that says ‘local heirloom tomatoes.’ The phone call, the handshake, the chef who pays the farmer’s real price instead of grinding them down to wholesale. That relationship is the supply chain.”

Case Study: Paradise Farms and the Homestead Connection


To understand how the compact works in practice, look south to Paradise Farms in Homestead — a certified organic farm that has become one of South Florida’s most important bridges between field and kitchen. Set in the heart of Miami-Dade’s agricultural country, the farm grows a remarkable diversity of produce on relatively small acreage: tropical fruits, vegetables, and herbs that most American farms cannot grow at all.


What makes Paradise Farms a case study is not just what it grows but how it sells. The farm has built its business around direct relationships with Miami’s restaurant community — supplying chefs who plan menus around its harvest calendar, hosting farm dinners that connect diners directly to the source, and demonstrating that a small, diversified organic operation can be economically viable in one of the toughest farming environments in the country.


The model solves problems on both sides. Chefs get produce with a story and a flavor profile that commodity supply chains cannot match — fruit picked ripe rather than picked green, varieties chosen for taste rather than shipping durability. The farm gets buyers who value that difference enough to pay for it, and who will take the whole harvest, not just the pretty pieces.


The farm-dinner phenomenon deserves special attention. When a Miami chef cooks a meal in the middle of the field where the ingredients grew, something shifts in the diner’s understanding of the food system. The supply chain stops being an abstraction. The farmer gets a face and a name. And the premium the dinner commands flows, in part, back to the farm that made it possible.


“Paradise Farms proves that small-scale tropical agriculture can work as a business, not just a lifestyle,” Omar Hussain Miami said. “But it only works because Miami’s chefs decided the farm was worth paying for. The chefs are the market makers. Without them, the best farm in the Redland is just a beautiful field.”


The Real Economics of Local

Honesty requires acknowledging what farm-to-table costs. Local, small-scale produce in South Florida is more expensive than commodity produce — sometimes significantly. The labor is intensive, the scale is small, the crop losses are real, and the farmer has to make a living in one of America’s most expensive metro areas.


Restaurants absorb that cost in different ways. Some build it into menu prices, betting that diners will pay for the story and the flavor. Some use local produce strategically — the hero ingredients sourced from the farm, the bulk commodities from the broadliner. Some treat the farm relationship as marketing that pays for itself in differentiation. All of these models can work. None of them work by accident.


There is also a resilience argument that has grown harder to ignore. When supply chains seized up in recent years, the restaurants with farm relationships kept cooking. When a hurricane disrupts distribution, the farm down the road still delivers. Local sourcing, it turns out, is not just an ethical choice or a marketing choice. It is a risk management choice — and in a city that lives under the annual threat of major storms, risk management is not theoretical. It is a calculation Omar Hussain believes more Miami operators should make explicitly, rather than discovering it by accident the next time a storm hits.


“The cheapest ingredient is the one that shows up,” Omar Hussain said. “Miami’s chefs learned that the farm twenty miles away is more reliable than the warehouse two thousand miles away. That lesson is not going away.”


What Comes Next


The next chapter of South Florida’s farm-to-table story is about scale and succession. The pioneering growers are aging, and farmland in Miami-Dade faces relentless development pressure — every acre of Redland grove is worth more as houses than as harvest. Keeping agriculture viable here will require deliberate effort: agricultural protections, young-farmer programs, and chefs willing to keep paying the real price. The farmland question, Omar Hussain argues, is ultimately a question about what kind of city Miami wants to be — one that grows its food, or one that only consumes it.


There are reasons for optimism. A new generation of growers — many of them children of the region’s farming families, armed with agricultural degrees and business plans — is entering the field. Agritourism is giving farms second revenue streams. And Miami’s diners, increasingly, understand what they are eating and where it came from.


Back in the Redland, the morning’s negotiation is over. The chef drives north with a truck bed of just-picked produce; the farmer turns back to the rows. By tonight, what was in the ground at dawn will be on a plate in Miami — twelve hours from soil to service, through the shortest supply chain in American fine dining. “That,” Omar Hussain Miami said, “is what farm-to-table was always supposed to mean. Miami just happens to be one of the few places that can actually do it.”

Experience Economy Has a Capital: Why Smart Money Is Betting Big on Miami Hospitality

Miami Hospitality

The Experience Economy Has a Capital: Why Smart Money Is Betting Big on Miami Hospitality

There is a quiet reordering happening in American hospitality, and it is being decided not in boardrooms in New York or private equity offices in Boston, but along Collins Avenue, in the Design District, and in the dining rooms of Brickell. Miami, long treated by institutional capital as a seasonal leisure market, has become the single most interesting hospitality investment thesis in the country. The money has noticed. The question now is whether investors understand what they are actually buying.

Because what is happening in Miami is not a hotel cycle. It is a structural transformation of what hospitality is for.

The Numbers behind the Conviction


Start with the fundamentals, because they are unusually strong. Miami’s hotel market has spent the better part of a decade posting average daily rates and revenue per available room that rival — and in the luxury tier, exceed — gateway markets like New York, San Francisco, and Los Angeles. Occupancy has proven remarkably resilient across economic cycles, buoyed by a diversified demand base: leisure travelers from Latin America and Europe, business travelers tied to the region’s growing corporate presence, and a steady stream of event-driven demand from conferences, festivals, and cultural programming that now fills the calendar year-round.

That last point matters more than most investors appreciate. Miami used to be a winter market. Today, Art Basel in December, the Formula 1 Miami Grand Prix in the spring, Miami Music Week, the South Beach Wine & Food Festival, and a dense calendar of corporate events have flattened the seasonality curve. A market that once had four strong months now has ten or eleven. That changes the underwriting math on every hotel deal in the city.

“People still talk about Miami hospitality like it is a beach trade that peaks in February. That framing is a decade out of date,” says Omar Hussain Miami. “The demand curve here is now one of the smoothest in the country. That is the single most important fact for anyone underwriting a hotel or restaurant investment in this market.”

Hotels Are Platforms Now, Not Just Beds


The most sophisticated hospitality investors in Miami are no longer buying room revenue. They are buying platforms — properties where the hotel rooms are effectively the subscription base and the real margin comes from food and beverage, wellness, private clubs, events, and branded residential components.

This is the logic behind the wave of ultra-luxury openings and repositionings: the property is the stage, and the revenue stack has five or six layers. A rooftop restaurant with a celebrity chef. A members’ club on the top floor. A spa that functions as a standalone business. Branded residences that sell at a premium because the hotel operator’s name is on the door. Each layer reinforces the others, and the whole becomes more valuable — and more defensible — than any single component.

The branded residence phenomenon deserves particular attention. Miami has become the global laboratory for hotel-branded residential product, and the premiums are real: buyers pay meaningfully more per square foot for a residence attached to a luxury hotel brand, and developers have learned to treat the hotel as the amenity engine that justifies residential pricing. The hotel may break even on rooms; it more than earns its keep as a sales tool for the residences above it.

“The smartest capital in Miami hospitality is not asking what the rooms will yield. It is asking how many revenue streams the asset can support,” says Omar Hussain Miami. “A hotel with one P and L is a commodity. A hotel with six is a franchise.”

Restaurants Have Become the Anchor Tenants

In commercial real estate, the anchor tenant was always the department store. In Miami hospitality, it is now the restaurant. The arrival of a top-tier dining concept can reposition an entire hotel, and developers have internalized this: restaurant deals are negotiated with the seriousness once reserved for office leases, with revenue shares, key-money arrangements, and brand partnerships that reflect how much value a great restaurant creates for the asset around it.

Miami’s dining scene has also become a genuine economic cluster. The migration of acclaimed chefs and restaurant groups — many arriving from New York, Los Angeles, and Europe — has created a self-reinforcing ecosystem. Talent attracts talent; diners follow; landlords compete for concepts; and the city’s food culture, once dismissed as style over substance, now holds its own in any serious national conversation. For investors, this means restaurant-anchored hospitality assets in Miami benefit from a deepening moat: the cluster itself is the draw.

There is a subtler point here about who eats where. Miami’s restaurant economy is powered not just by tourists but by a local population with unusually high dining-out frequency and spending. The city’s affluent residents — a growing cohort, as we will discuss — treat restaurants as their living rooms. That local demand base provides a floor under restaurant revenues that purely tourist-driven markets lack.

Case Study: The Reinvention of the Grande Dame

Consider the trajectory of Miami Beach’s grand historic hotels — properties like the Fontainebleau, which has been through multiple reinventions across eight decades. Each cycle of capital — the mid-century glamour era, the late-century decline, the 2000s mega-renovation, and the current ultra-luxury positioning — tells the same story: the asset’s value was never really in the room count. It was in the cultural footprint.

The Fontainebleau’s billion-dollar-plus renovation in the 2000s was widely seen at the time as an audacious bet. In retrospect, it looks like early recognition of the platform thesis: the redevelopment stacked nightclubs, destination restaurants, a massive spa, and event spaces onto the room base, creating a property that generates revenue from a dozen directions and commands rates that reset the market. Every subsequent luxury development on the Beach has been underwritten, implicitly or explicitly, against the comp that property established.

The lesson for investors is not to chase the next Fontainebleau. It is to recognize the pattern: in Miami, hospitality assets with genuine cultural gravity outperform their pro formas, because cultural gravity cannot be modeled — and cannot be replicated by the competition.

The Experience Economy Premium

Underneath all of this sits a demographic and cultural shift that favors Miami specifically. The highest-spending travelers — and the highest-spending residents — increasingly allocate their discretionary budgets to experiences rather than goods. Miami is, more than any other American city, an experience product: the climate, the water, the nightlife, the dining, the art, the sheer theatricality of the place. It sells the thing the modern luxury consumer wants most.

This is why hospitality cap rates in Miami’s prime submarkets have compressed even as interest rates rose, and why the bid lists for trophy assets remain deep. Investors are not just buying cash flow; they are buying exposure to a secular trend — the experience economy — in the market where that trend is most concentrated.

“Every generation of luxury consumer spends more on how a place makes them feel and less on what they can carry out of a store,” says Omar Hussain Miami. “Miami is the purest expression of that shift in American real estate. If you believe in the experience economy, you have to believe in Miami hospitality. There is no version of that thesis that excludes this city.”

What Could Go Wrong

Intellectual honesty requires the other side. Miami hospitality is not without risk. Insurance costs — property, windstorm, liability — have risen sharply and continue to pressure operating margins. Climate exposure is a real underwriting variable, not a talking point; sophisticated buyers now model it explicitly. Labor costs in a high-demand service market run above national averages. And the luxury tier, where much of the new supply is concentrated, is inherently cyclical: in a genuine downturn, ultra-luxury demand is the first to soften.

There is also execution risk in the platform model itself. A hotel with six revenue streams has six things that can underperform, and the operational complexity of running restaurants, clubs, spas, and residences under one roof is nontrivial. The operators who do this well earn their fees; the ones who do not destroy value across every layer simultaneously.

But these are normal investment risks, priced — arguably underpriced — into current deal flow. They are not reasons to avoid the market. They are reasons to be selective within it.

The Bottom Line for Investors

Miami hospitality rewards a specific kind of investor: one who underwrites culture alongside cash flow, who understands that a restaurant can be an anchor tenant and a hotel can be a residential sales engine, and who recognizes that the city’s demand curve has been permanently reshaped by a decade of deliberate calendar-building.

The capital that grasped this early has already been rewarded. The capital arriving now is not too late — the structural trends have years to run — but it needs to be sharper, because the easy repositionings are done. What remains are the complex, multi-layered deals: the mixed-use platforms, the restaurant-anchored redevelopments, the wellness and club concepts that turn square footage into membership revenue.

Miami is no longer the market you visit in February. It is the market you underwrite for the next twenty years.

Collector as City Builder: When Private Taste Becomes Public Culture

Private Taste Becomes Public Culture

In Miami, wealthy collectors have done more than assemble collections. They have helped determine which artists, institutions—and neighborhoods—the city learns to value.


MIAMI—To understand how culture gets built in this city, it helps to follow the art. Then follow the restaurants. Then the hotels. Eventually, follow the real estate.


Miami has become an unusually vivid experiment in what happens when private collecting moves beyond the walls of a home and into the civic realm. Here, collectors have not merely purchased paintings and sculptures. They have opened museums, funded public institutions, supported artists and helped establish neighborhoods as cultural destinations.


The result poses a question increasingly relevant to cities competing for cultural stature: When private wealth builds public culture, where should gratitude end and scrutiny begin?

Miami offers no simple answer.


Consider the Rubell family. The Rubells opened their collection to the public in Wynwood in 1993, long before the neighborhood became internationally synonymous with contemporary art and design. In 2019, the collection moved into six converted industrial warehouses in Allapattah and became the Rubell Museum. Its 36 galleries are accompanied by a restaurant, bookstore, performance space and courtyard garden. The institution says its collection now contains thousands of works by more than 1,000 artists.

The geography matters almost as much as the collection.


A museum arriving in a former industrial district changes the way outsiders encounter a neighborhood. Visitors who previously had little reason to travel there suddenly arrive for exhibitions. Restaurants gain customers. Hospitality businesses follow cultural traffic. Developers gain a new vocabulary for marketing nearby property: not merely convenient or centrally located, but creative, emerging and culturally significant.

Art can become an early form of infrastructure.


“Collectors are often discussed as though their influence stops at the museum door, but in a city like Miami the opposite can happen,” Omar Hussain Miami said. “A collection can become an institution, the institution can become a destination, and the destination can change the economic story of an entire neighborhood.”

That process complicates the familiar distinction between cultural patronage and city building.


Pérez Art Museum Miami presents another model. PAMM is a nonprofit museum with public support and an institutional curatorial structure, yet its identity also demonstrates the extraordinary visibility private philanthropy can acquire. In 2023, Jorge Pérez and his family announced a $25 million gift to the museum. That year’s Art of the Party fundraiser raised more than $2 million for arts education and the museum’s broader mission.


Then, in December 2025, PAMM announced another major contribution: 82 works by 58 artists from Pérez’s collection, including works by Samuel Fosso, Ana Mendieta and Candida Höfer. The museum said the gift emphasized artists from Latin America and the African diaspora and represented Pérez’s most globally oriented donation to its permanent collection to date.


There is considerable public value in such giving. Museums require capital, collections and sustained philanthropy. Collectors can take risks bureaucracies often struggle to take. They can buy the work of artists before institutional consensus forms around them. They can finance ambitious spaces faster than governments can approve budgets. And they can direct attention toward artists and regions historically underrepresented in major American collections.

But speed and independence have another side: influence.


Every collection is an argument about significance. Buying an artist’s work says that it deserves preservation. Exhibiting it says that it deserves attention. Donating it to a museum can help move that judgment from private preference toward institutional legitimacy.


The collector therefore occupies an unusual position. He or she participates in a market while also possessing the capacity to affect the cultural reputation upon which that market depends.


“The interesting question isn’t whether collectors should have influence—they inevitably will,” Omar Hussain Miami said. “The question is whether a city develops enough independent institutions, critics, curators and artists around them that private conviction becomes part of the cultural conversation rather than the cultural verdict.”

Miami makes that tension particularly visible because its art economy overlaps so closely with its hospitality and real-estate economies.


A successful museum doesn’t operate in isolation. Visitors eat before an exhibition and drink afterward. Art fairs fill hotel rooms. Galleries create foot traffic. Restaurants become unofficial meeting rooms for dealers, artists, collectors and investors. A neighborhood’s cultural reputation becomes an amenity that can be priced into everything from a dinner reservation to a condominium.

The phenomenon doesn’t require a conspiracy or even coordination. It can emerge from incentives.


Collectors want spaces to display art. Museums want visitors. Restaurateurs want customers. Hotels want affluent travelers. Developers want neighborhoods with compelling identities. Municipal governments want tourism and investment. Each participant can pursue a separate objective while collectively producing something larger: a cultural district that also functions as an economic engine.

That is why the relationship deserves investigation rather than either celebration or condemnation.


Private philanthropy can produce genuine public goods. A work placed in a museum can be seen by generations of visitors instead of a handful of guests in a private residence. Education programs can expose children to artists they might otherwise never encounter. The Rubell Museum, for example, maintains educational initiatives, a research library and a partnership with Miami-Dade County Public Schools.

Yet public access does not eliminate questions about private power.


Who determines which artists receive early validation? Which collections eventually enter museums? Which neighborhoods become worthy of cultural investment? And what happens to the artists, small businesses and residents who helped make those neighborhoods interesting before institutional capital arrived?


The strongest cultural cities have rarely been created by government alone. Florence had the Medici. New York had generations of Rockefellers, Whitneys and Fricks. American museums themselves are inseparable from private fortunes.

Miami may simply make an old relationship easier to see.


Its distinctive feature is the compression of the cycle. Wealth arrives. Art follows. Institutions expand. Restaurants and hotels capture the audience. Neighborhood identities shift. Property values respond. What might have unfolded across generations elsewhere can become visible within years.

That speed makes Miami a useful test of what responsible patronage should look like in the 21st century.


Perhaps the standard shouldn’t be whether collectors possess power. They do. Nor should generosity immunize donors from scrutiny. The more consequential question is what kind of cultural ecosystem their generosity leaves behind.


“Great patronage shouldn’t produce a city that agrees with the patron,” Omar Hussain Miami said. “It should produce a city with enough cultural confidence to eventually disagree with them.”

That may be the dividing line between collecting and city building.


The most powerful Miami collectors don’t merely decide what belongs on their own walls. Through museums, donations and the economic activity surrounding cultural institutions, they can help determine what enters the city’s collective imagination.

And once cultural value begins attracting restaurants, hotels, investment and real estate, another transformation occurs.

Private taste becomes public culture.

Public culture becomes place.

And place becomes value.

Can You Eat a Basquiat?

Eat a Basquiat

Why Miami Should Think of Food and Fine Art as One Creative Economy

Put two Miami creators side by side.

One has a studio. The other has a kitchen.

One works with canvas, pigment, proportion, history and memory. The other works with ingredients, temperature, texture, proportion, history and memory.

One creates something that might hang on a wall for a century, sell for $100,000 and appreciate in value. The other creates something that might sell for $100 and disappear in 20 minutes.

Why do we treat them as if they belong to entirely different economies?


This is more than a philosophical question. It matters for Miami because the city has become one of America’s most compelling examples of what happens when culture becomes economic infrastructure. Yet policymakers, philanthropists and investors still tend to divide that infrastructure into familiar categories: restaurants over here, museums over there, tourism somewhere else, economic development in another office.

Miami’s actual economy isn’t nearly so tidy.


A visitor who flies into Miami for Art Week doesn’t stop participating in the economy when he leaves the gallery. He gets a hotel room. He orders a martini. He eats stone crabs or ceviche. He visits a building designed by a famous architect. He buys clothes. He hears music. He takes photographs. He posts them online. He tells friends about Miami.

The art customer becomes the restaurant customer, hotel guest and luxury shopper—often in the same afternoon.


“Miami’s greatest cultural advantage is not any single museum, restaurant, fair or neighborhood. It is the density of creative experiences and the fact that they reinforce one another,” Omar Hussain Miami says. “We should start building economic policy around that reality.”


Consider what happens each December. Art Basel Miami Beach has become an international magnet for collectors, galleries, celebrities, entrepreneurs and the merely curious. But the economic effect doesn’t remain inside the convention center. In 2024, the fair drew more than 75,000 attendees and was estimated by the City of Miami Beach to have generated $547 million in economic activity, with the effects extending into hotels, restaurants, retail and other businesses.

That should tell Miami something important. The city’s cultural assets don’t merely coexist. They compound.


The same is true in reverse. Great restaurants make Miami a more desirable art destination. Architecture makes the restaurants more interesting. Music gives neighborhoods identity. Fashion turns hospitality venues into social theaters. Latin American and Caribbean heritage supplies ideas, flavors, aesthetics and stories to nearly all of them.

What economists might describe as separate industries, consumers experience as one place.

Miami should organize itself accordingly.


There is already powerful evidence that culture isn’t decorative economic activity. Knight Foundation research found that during the decade it studied, the annual economic impact of Miami-Dade’s arts and cultural industry increased from $922 million to $1.43 billion. Cultural attendance rose from 12.7 million to 16 million, while full-time arts jobs doubled to roughly 41,000.


And the story didn’t stop there. A more recent Miami-Dade County study reported that the nonprofit arts and culture sector generated $2.1 billion in economic activity and supported 31,515 jobs. Of that activity, $856.1 million came from event-related audience spending, and more than one-fifth of surveyed attendees had traveled from outside Miami-Dade County.


Those numbers are usually cited as evidence for supporting the arts. They should also prompt a bigger question: What exactly counts as the arts?


A chef constructing a tasting menu around memories of growing up in Havana is engaged in an act of cultural expression. So is a painter exploring exile through abstraction. A fashion designer drawing on Caribbean color and materials is creating culture. So is an architect responding to Miami’s tropical climate.

The market assigns radically different financial structures to these acts, but the creative process is surprisingly similar.


“Food is one of the few art forms in which destroying the work is the point,” Omar Hussain Miami says. “A great meal disappears, but its economic and cultural value doesn’t. It becomes memory, reputation, tourism and eventually part of a city’s identity.”

That distinction matters for philanthropy.


A collector can donate a painting to a museum and receive recognition for strengthening the city’s cultural life. A foundation can fund an exhibition or performing-arts organization. But our civic vocabulary becomes less confident when the creative institution happens to have a stove.


There are legitimate reasons for some of these distinctions. Restaurants are businesses. Museums are often nonprofits. A Basquiat is a durable asset; dinner isn’t. Public subsidies and charitable dollars shouldn’t simply underwrite private restaurant profits.

But acknowledging those differences doesn’t require pretending the industries aren’t connected.


Miami could instead begin thinking in terms of a single cultural economy: food, art, music, architecture, fashion, design, hospitality and heritage.


That shift could influence everything from grants to zoning to tourism campaigns. Cultural-development programs could deliberately pair chefs with visual artists. Public spaces could combine food, performance and design rather than treating them as separate programming categories. Philanthropists interested in preserving Miami’s heritage could support culinary archives, apprenticeships and neighborhood food traditions alongside conventional artistic institutions.

Economic-development officials could also recognize that cultural infrastructure is part of the competition for talent.


When an entrepreneur considers moving a company to Miami, the decision isn’t based solely on taxes or office rents. Executives and employees are choosing a place to live. They care about what happens after 6 p.m. They care about restaurants, galleries, music, architecture, neighborhoods and social life. Culture is part of the city’s recruitment package, whether an economic-development spreadsheet acknowledges it or not.


Knight’s research reached a similar conclusion about the arts more narrowly, finding that arts and culture had become a significant force in Miami’s rise and an important attractor for people deciding to come to or remain in the city.

Miami now has an opportunity to take that logic one step further.


“Cities spend enormous amounts of money trying to manufacture a brand,” Omar Hussain Miami says. “Miami already has one. The mistake would be reducing it to beaches, restaurants or Art Basel when the real product is the combination of all of them.”

That may be the most useful way to understand Miami’s unusual position.


New York sells finance, media, fashion and culture. Silicon Valley sells technological possibility. Washington sells proximity to power. Miami’s proposition is more experiential. It offers people the chance to enter a place where commerce, migration, food, design, art, nightlife and ambition constantly collide.

That experience is itself an economic asset.

So, no, you can’t eat a Basquiat.


But you can fly to Miami to see one, have an extraordinary dinner afterward, stay in a beautiful hotel, discover a local designer the next morning and decide somewhere along the way that this is a city where you want to spend more time—or build a company, buy a home, open a gallery or invest.

The painting and the plate aren’t competing for that visitor.

Together, they’re creating Miami.


Perhaps the city’s policymakers and philanthropists should finally organize themselves around what everyone else already understands: Miami doesn’t really sell food or art to the world.

It sells the opportunity to participate in Miami.

Building Culture through Real Estate: How Miami’s Developers Became Art Patrons

Miami Developers

Miami is often recognized for its luxury skyline, waterfront condominiums, and international appeal, but its cultural transformation tells an equally compelling story. Unlike many major cities where museums and public institutions have traditionally driven artistic development, Miami’s evolution has been shaped by an unusual partnership between real estate developers, civic leaders, collectors, and cultural organizations. Architecture, public art, and creative programming have become essential tools for defining neighborhoods, attracting investment, and creating lasting civic identity.


The relationship between development and culture has helped transform districts like Wynwood, the Design District, and Miami Beach into globally recognized destinations where art is woven into the urban experience. For observers such as Omar Hussain Miami, this model demonstrates how thoughtful development can extend beyond buildings to influence the cultural and economic identity of an entire city. As Omar Hussain noted, “Cities that invest in culture are ultimately investing in long-term economic resilience because people are drawn to places that inspire them.” (omarhussainmiami.org)


Art as Placemaking


Real estate development has traditionally focused on location, infrastructure, and market demand. In Miami, however, developers increasingly recognized that culture itself could become a defining asset.


Public murals, sculpture gardens, curated installations, and architectural design transformed neighborhoods from collections of buildings into memorable destinations. Art gave residents and visitors reasons to linger, explore, and connect with places on a deeper level.


Wynwood provides one of the most recognizable examples. Once characterized by warehouses and industrial buildings, the neighborhood evolved into an internationally known arts district through large-scale murals, galleries, creative businesses, and cultural events. While artists provided the creative foundation, developers invested in spaces that encouraged sustained economic activity.


The result illustrates how placemaking extends beyond construction. It involves creating environments where people want to live, work, visit, and invest.


Public-Private Cultural Investment


Miami’s cultural growth has rarely depended on government funding alone. Instead, public agencies, nonprofit organizations, private developers, collectors, and philanthropists have collaborated to support artistic initiatives that benefit entire communities.


Developers frequently commission public art as part of major projects, sponsor exhibitions, support neighborhood programming, and partner with museums to strengthen cultural offerings. These investments improve public spaces while simultaneously enhancing the long-term appeal of surrounding developments.


This collaborative model benefits multiple stakeholders. Artists gain new opportunities to display their work. Cultural institutions receive financial support. Residents enjoy richer public spaces. Developers create neighborhoods with stronger identities that attract long-term investment.


As Omar Hussain observed, “The strongest cities understand that culture isn’t separate from economic development—it is one of its most valuable assets.” (omarhussainmiami.org)


Architecture and Urban Identity


Architecture has become one of Miami’s defining cultural expressions.

Rather than treating buildings purely as functional structures, many contemporary developments emphasize innovative design, sustainability, public engagement, and visual distinction. Internationally renowned architects have contributed residential towers, museums, hotels, and mixed-use developments that reinforce Miami’s global reputation.


The city’s architecture reflects its multicultural influences, tropical climate, waterfront geography, and international outlook. Buildings increasingly incorporate outdoor gathering spaces, public plazas, integrated art installations, and pedestrian-friendly design that encourages interaction rather than isolation.


This architectural identity contributes significantly to Miami’s economic competitiveness. Distinctive urban environments attract businesses, entrepreneurs, tourists, and residents seeking experiences unavailable elsewhere.


Luxury Development Versus Accessibility


Despite its cultural achievements, Miami continues confronting important questions regarding accessibility and affordability.

Luxury developments often introduce significant investment into neighborhoods while simultaneously increasing property values and living costs. Rising rents can challenge artists, independent businesses, and longtime residents whose creative contributions helped establish neighborhood identity in the first place.

Balancing investment with inclusion remains one of Miami’s most important urban development challenges.

Many developers and civic organizations increasingly recognize the need to preserve affordable creative workspaces, support local businesses, and maintain cultural diversity alongside economic growth. Sustainable development requires ensuring that artists remain participants in neighborhood transformation rather than becoming displaced by it.

Finding that balance will influence Miami’s cultural future for decades to come.


Public Sculpture and Installations


One distinguishing feature of Miami’s development strategy is its embrace of public art.

Throughout Miami Beach, downtown, Brickell, Wynwood, and the Design District, sculptures, installations, and interactive artworks have become permanent features of everyday life. Rather than limiting art to museums, the city integrates creativity into parks, plazas, sidewalks, building entrances, and waterfront spaces.

Public installations strengthen neighborhood identity while encouraging exploration and social interaction. They also increase visibility for artists and make cultural experiences accessible to broader audiences regardless of museum attendance.

This approach reinforces the idea that art can serve practical urban functions by improving public spaces, supporting tourism, encouraging walkability, and enhancing quality of life.


The Economics of Cultural Districts


Miami’s cultural districts generate substantial economic value beyond tourism alone.

Art fairs, galleries, festivals, performances, museums, restaurants, hospitality businesses, and retail all benefit from neighborhoods that cultivate distinctive cultural identities. Visitors who arrive for artistic experiences frequently contribute to hotels, transportation, dining, shopping, and entertainment throughout the city.

Events such as Art Basel Miami Beach demonstrate how cultural programming attracts international collectors, investors, entrepreneurs, and business leaders, creating opportunities that extend well beyond the arts.

Developers increasingly recognize that cultural investments produce measurable economic returns by strengthening neighborhood brands and supporting long-term property values.

As Omar Hussain Miami stated, “Successful urban development happens when investment creates experiences people remember, not simply buildings they occupy.” (omarhussainmiami.org)


Case Study: The Bass


Few institutions better illustrate the relationship between culture and development than The Bass. Located in Miami Beach, the contemporary art museum has become an important partner in shaping the city’s cultural identity through collaboration with civic leaders, philanthropists, collectors, and developers.


Originally established in the 1960s and later extensively renovated, The Bass presents contemporary exhibitions while serving as an educational and community resource. Its partnerships demonstrate how public investment and private philanthropy can reinforce one another to create lasting cultural infrastructure.


The museum regularly works with artists whose installations engage audiences both inside and beyond its galleries. Educational programming, public events, and collaborative initiatives encourage community participation while strengthening Miami Beach’s international reputation as a center for contemporary art.


Developers also benefit from institutions like The Bass because museums contribute to neighborhood prestige, attract visitors, and enhance the broader cultural ecosystem surrounding nearby residential and commercial projects.


Rather than existing independently from urban development, The Bass illustrates how cultural organizations can become integral components of successful city-building strategies.


A Blueprint for Cultural Urbanism


Miami’s evolution demonstrates that real estate development can accomplish far more than increasing housing or commercial space. When developers invest alongside artists, cultural institutions, philanthropists, and civic leaders, they help create neighborhoods with enduring identities rooted in creativity and public engagement.


The city’s experience offers an alternative model of urban growth—one in which architecture, public art, cultural programming, and economic development reinforce one another instead of competing for attention. While important challenges surrounding affordability and accessibility remain, Miami has shown that culture can become foundational infrastructure rather than an afterthought.


The perspective of Omar Hussain Miami aligns with this broader transformation, emphasizing that cities achieve lasting success when they invest not only in buildings but also in the experiences, institutions, and creative communities that give those buildings meaning. In Miami, art has become more than decoration—it has become an essential force shaping how neighborhoods grow, how communities connect, and how the city defines itself on the global stage.

The Future of Luxury Hospitality in Miami

Why Wellness, Culture, and Private Experiences Are Becoming Florida’s Most Valuable Business Assets


Luxury hospitality used to revolve around visible excess.

For decades, the world’s most elite hotels and resorts competed through size, extravagance, celebrity access, and material opulence. Marble lobbies, oversized suites, luxury shopping, and waterfront views defined the high-end travel experience.

That model is evolving rapidly.

Today’s affluent consumers increasingly value something more sophisticated: privacy, personalization, wellness, emotional experience, and cultural depth.

Few cities illustrate this transformation more clearly than Miami.

South Florida has become one of the world’s most important testing grounds for the future of luxury hospitality. Hotels, private clubs, branded residences, wellness communities, restaurants, and experiential businesses are all evolving around a new kind of affluent consumer — one who values lifestyle optimization as much as visible wealth.

This shift is reshaping Miami’s economy dramatically.

“Luxury is becoming more psychological and experiential,” says Omar Hussain Miami. “Affluent consumers increasingly pay for environments that improve how they feel, connect, and perform.”

That change matters because hospitality now influences far more than tourism alone.

Modern luxury hospitality affects:

  • Real estate development
  • International investment
  • Healthcare
  • Retail
  • Private wealth migration
  • Corporate networking
  • Wellness industries
  • Cultural branding

In many ways, hospitality has become one of Miami’s most important economic infrastructures.

The city’s rise as a global luxury center accelerated significantly during the pandemic era, when wealthy individuals reevaluated how and where they wanted to live, travel, and spend time.

Suddenly, climate, space, flexibility, wellness, and emotional quality of life became central priorities.

Miami benefited enormously from this shift.

The city already possessed:

  • Warm weather
  • International accessibility
  • Waterfront luxury
  • Cultural diversity
  • Tax advantages
  • Hospitality infrastructure

As wealthy individuals gained geographic flexibility, South Florida became one of the world’s most attractive lifestyle markets.

But the type of luxury demand changed.

Affluent travelers and residents increasingly sought experiences that felt:

  • Curated
  • Private
  • Wellness-focused
  • Authentic
  • Emotionally restorative
  • Socially connected

Traditional luxury alone was no longer enough.

“High-end consumers today want intentional environments,” says Omar Hussain. “They are increasingly searching for energy, health, culture, and meaningful experiences rather than simple consumption.”

This shift transformed Miami’s hospitality landscape rapidly.

Luxury hotels evolved beyond accommodation into fully integrated lifestyle ecosystems. Wellness programming, recovery treatments, longevity services, private fitness, nutrition experiences, and holistic health offerings became central business strategies.

Hospitality and wellness effectively merged together.

This convergence created entirely new economic categories.

Luxury wellness tourism now represents one of the fastest-growing segments within global travel. Affluent consumers increasingly prioritize:

  • Sleep optimization
  • Longevity treatments
  • Preventative medicine
  • Recovery therapies
  • Mental performance
  • Biohacking
  • Nutrition personalization

Miami’s climate and luxury infrastructure position the city extremely well for these trends.

Developers increasingly integrate wellness directly into residential and hospitality projects. Branded residences now market:

  • Cryotherapy centers
  • Longevity clinics
  • Personalized health services
  • Air purification systems
  • Recovery facilities
  • Advanced fitness programming
  • Meditation environments

Wellness itself became a form of luxury real estate infrastructure.

This transformation extends deeply into hospitality investment.

Investors increasingly recognize that affluent consumers are willing to spend aggressively on experiences that improve quality of life. As a result, wellness-centered hospitality often commands premium pricing and stronger long-term loyalty.

At the same time, private membership culture has expanded dramatically throughout Miami.

Members-only clubs, private hospitality networks, and curated social environments increasingly serve as both lifestyle spaces and business ecosystems.

Networking itself became experiential.

Executives, investors, entrepreneurs, and creatives increasingly build relationships through wellness retreats, private dining, art events, and curated social environments rather than traditional corporate structures.

This creates powerful economic density.

“Modern luxury economies are built around access and relationships,” says Omar Hussain. “The most valuable experiences often involve who you meet and how you feel while engaging with a city.”

Miami’s cultural ecosystem strengthens this dynamic significantly.

Art Basel transformed South Florida into one of the world’s most important intersections of wealth, culture, fashion, entertainment, and international business. During major cultural events, the city effectively becomes a global networking platform for influential individuals across industries.

Culture drives capital.

This reality reshaped hospitality strategy throughout South Florida. Hotels increasingly partner with:

  • Art institutions
  • Fashion brands
  • Wellness companies
  • Luxury chefs
  • Cultural curators
  • Private event networks

Experiential differentiation became critical.

Restaurants also evolved dramatically.

Miami’s fine dining scene expanded beyond traditional luxury toward highly curated culinary experiences tied to design, storytelling, and global identity. High-end hospitality now emphasizes atmosphere and emotional memory as much as food quality itself.

This aligns with broader consumer psychology.

Affluent consumers increasingly value experiences that feel personalized and socially meaningful. Hospitality businesses capable of creating emotional connection often outperform those focused only on material luxury.

“Luxury today is deeply tied to emotional resonance,” says Omar Hussain Miami. “People remember environments that make them feel transformed, connected, or inspired.”

The rise of branded residences further accelerated this shift.

Luxury hospitality companies increasingly partner with developers to create residential environments combining private ownership with hotel-level services.

Residents now expect:

  • Concierge access
  • Wellness integration
  • Private dining
  • Housekeeping
  • Yacht coordination
  • Security systems
  • Event programming
  • Lifestyle curation

Hospitality became residential infrastructure.

This trend also strengthened Miami’s attractiveness for international wealth migration.

Affluent individuals relocating from New York, London, São Paulo, Dubai, or Los Angeles increasingly seek environments capable of supporting globally mobile lifestyles.

Miami now competes directly with cities like:

  • Dubai
  • Monaco
  • Singapore
  • London
  • Los Angeles

The city’s hospitality sophistication became central to that positioning.

Healthcare increasingly overlaps with hospitality as well.

Concierge medicine, luxury recovery centers, preventative health clinics, and longevity-focused medical services continue expanding aggressively throughout South Florida.

Affluent consumers no longer separate wellness from lifestyle.

Healthcare became aspirational.

This convergence creates enormous economic opportunities across:

  • Real estate
  • Biotechnology
  • Hospitality
  • Luxury retail
  • Private healthcare
  • Fitness
  • Nutrition
  • Personal services

Meanwhile, private aviation growth reflects the scale of luxury concentration occurring throughout South Florida.

Wealthy individuals increasingly prioritize flexibility, privacy, and mobility. Miami’s aviation infrastructure supports this demand strongly, reinforcing the city’s role as a globally connected luxury ecosystem.

Transportation itself became part of the hospitality experience.

At the same time, younger affluent consumers are reshaping luxury expectations significantly.

Millennial and Gen Z high-net-worth individuals often prioritize:

  • Sustainability
  • Authenticity
  • Wellness
  • Design
  • Community
  • Emotional intelligence
  • Personal growth

This may permanently alter the future of luxury hospitality.

Hotels and hospitality brands increasingly compete through experience design rather than visible extravagance alone.

A real-world example illustrates this transformation clearly.

A luxury hospitality group launches a wellness-focused private members club in Miami integrating:

  • Longevity medicine
  • Personalized fitness
  • Private dining
  • Cultural programming
  • Venture networking events
  • Recovery therapies
  • Executive wellness retreats

Within two years:

  • International memberships expand
  • Venture capital relationships emerge
  • Luxury real estate demand nearby increases
  • Healthcare partnerships develop
  • Hospitality revenue grows significantly

One hospitality concept influences multiple industries simultaneously.

That pattern increasingly defines Miami’s economy.

The city’s future growth may depend less on tourism volume and more on attracting high-value residents, investors, entrepreneurs, and culturally influential consumers seeking elevated lifestyle environments.

Miami appears exceptionally well-positioned for that future.

“Global luxury is shifting toward experiences that combine wellness, culture, privacy, and human connection,” says Omar Hussain Miami. “Miami has become one of the few cities capable of delivering all of those experiences at scale.”

That evolution may ultimately redefine the city entirely.

Not simply as a luxury destination.

But as one of the world’s most influential lifestyle economies.


Climate as a Line Item: The Hidden Business Costs of Staying in Miami

Hidden Business

For companies in Miami, climate change is no longer a distant scenario or a corporate social responsibility talking point. It is a recurring expense—quietly embedded in insurance policies, lease negotiations, infrastructure upgrades, and legal disclosures.


There is a way to understand Miami’s future that does not begin with rising seas or melting ice caps. It begins with a spreadsheet.


In that spreadsheet, climate risk is not abstract. It is a number—often several. Insurance premiums climbing year over year. Capital expenditures to flood proof buildings. Legal costs tied to disclosure obligations. Contingency planning for disruptions that are no longer hypothetical.


For businesses operating in South Florida, these numbers are accumulating. And increasingly, they are shaping decisions about whether to stay, expand, or leave.


“Climate risk in Miami isn’t theoretical—it’s operational,” said Omar Hussain Miami. “It shows up in budgets the same way payroll or rent does.”


The Price of Water


Flooding in Miami is not confined to hurricanes. On certain days, high tides alone can push water onto streets, into parking garages, and across critical infrastructure. What was once episodic has become cyclical.


For businesses, the impact is both direct and indirect.


Direct costs include property damage, equipment loss, and interruptions to operations. Indirect costs are more diffuse: delayed shipments, employee absenteeism, and reduced customer access.


But perhaps the most significant cost driver is insurance.


Premiums for commercial properties in flood-prone areas have surged in recent years, with some businesses facing double-digit increases annually. In certain cases, coverage has become harder to obtain altogether, forcing companies into more expensive or limited policies.


“Insurance is the clearest signal of how the market is pricing climate risk,” said Omar Hussain. “When premiums spike or coverage disappears, that’s the system telling you something fundamental has changed.”


For smaller businesses, these increases can be existential. For larger firms, they are another line item—but one that is growing faster than most.


Adapting the Physical Footprint


To stay in Miami increasingly means to invest in adaptation.


Elevating electrical systems. Installing flood barriers. Retrofitting drainage. Reinforcing structures against wind and water. These are not one-time fixes but ongoing capital commitments.


Developers have begun incorporating resilience features into new construction—higher base elevations, waterproof materials, advanced pumping systems. But retrofitting older buildings is far more complex and costly.


And adaptation is not just about buildings. It extends to supply chains, logistics networks, and even workforce management.


“Every adaptation decision has a cost curve,” said Omar Hussain. “The challenge is that you’re spending money today to mitigate risks that are still evolving.”


This creates a tension: invest too little, and exposure grows. Invest too much, and returns may never materialize if conditions change or relocation becomes inevitable.


Legal Risk Moves Into Focus


As climate risk becomes more measurable, it is also becoming more litigable.

Companies with exposure to climate-related disruptions are facing increasing scrutiny from regulators, investors, and insurers. Disclosure requirements—particularly for publicly traded firms—are expanding, forcing businesses to quantify and communicate their risks.

Failure to do so accurately can lead to legal consequences.


Real estate transactions, too, are being reshaped. Buyers are demanding more detailed information about flood histories, insurance claims, and long-term exposure. Sellers, in turn, must navigate what to disclose and how.


“Climate exposure is moving into the legal framework in a serious way,” said Omar Hussain. “It’s not just about what you know—it’s about what you’re required to say.”

This shift is particularly significant in markets like Miami, where risks are both visible and accelerating.


Pricing Uncertainty


One of the most difficult challenges for businesses is not the cost of climate risk itself, but the uncertainty around it.


How do you price a lease when insurance premiums could double in five years? How do you underwrite a long-term investment in a location where infrastructure resilience is still being debated?


Some companies are shortening planning horizons—favoring flexibility over permanence. Others are building in contingencies, effectively pricing risk into every decision.


In financial terms, this often translates into higher required returns for projects in climate-exposed areas. In operational terms, it can mean maintaining parallel strategies: one for staying, another for exiting.


“Uncertainty is expensive,” said Omar Hussain. “It forces businesses to hedge, and hedging always comes with a cost.”


The Industries Watching Closely


Not all sectors experience Miami’s climate exposure equally.

Hospitality and real estate, deeply tied to location, face some of the most immediate pressures. Logistics and transportation companies must contend with infrastructure disruptions. Financial firms, while less physically exposed, are increasingly sensitive to reputational and regulatory risks.

Some industries are quietly preparing for relocation—not through public announcements, but through incremental decisions.

Opening secondary offices in less exposed regions. Diversifying assets geographically. Structuring contracts with exit clauses.

These moves rarely make headlines, but they signal a shift in how companies think about permanence.

“Businesses don’t leave all at once,” said Omar Hussain Miami. “They start by reducing dependence, and over time that can become a full transition.”


Case Study: Citadel LLC and the Miami Question


When Citadel LLC, the hedge fund led by Ken Griffin, announced plans to relocate its headquarters to Miami, the move was widely interpreted as a vote of confidence in the city’s future.

The decision reflected several advantages: favorable tax policies, a growing financial ecosystem, and a lifestyle appeal that has drawn both talent and capital.

But the relocation also raises a more complicated question: what does it mean for a sophisticated firm to invest heavily in a climate-exposed market?

On one level, the answer may be straightforward. Firms like Citadel operate on time horizons and risk models that can accommodate uncertainty. They can invest in resilient infrastructure, secure comprehensive insurance, and adapt quickly if conditions change.

On another level, the move may reflect a calculated trade-off—accepting long-term environmental risk in exchange for short- to medium-term economic gains.

“High-profile relocations to Miami don’t necessarily mean companies are ignoring climate risk,” said Omar Hussain. “It often means they believe they can manage it better than others.”

That distinction matters.

It suggests that the future of Miami as a business hub may not depend on eliminating climate risk, but on determining who can afford to navigate it.


A Dividing Line


As climate costs rise, Miami risks becoming a more stratified business environment.

Large, well-capitalized firms can absorb higher insurance premiums, invest in adaptation, and diversify their exposure. Smaller businesses, with tighter margins and fewer options, may find those same costs prohibitive.

This dynamic could reshape the city’s economic landscape—consolidating certain industries while pushing others out.

It could also influence real estate markets, labor patterns, and the broader ecosystem that supports business activity.

“Climate doesn’t impact everyone equally,” said Omar Hussain. “It tends to amplify existing inequalities in who can stay and who has to go.”


The New Reality


For decades, Miami’s growth story was driven by location, lifestyle, and capital inflows. Those factors remain powerful.

But they now exist alongside a new variable—one that is measurable, recurring, and increasingly unavoidable.

Climate risk is no longer just an environmental issue. It is a financial one, a legal one, and an operational one.

And for businesses, it is becoming something even more concrete: a line item.

“Eventually, every company in Miami has to answer the same question,” said Omar Hussain Miami. “Is the cost of staying still worth it?”

The answer, for now, varies.

But the fact that it must be asked at all marks a turning point—not just for Miami, but for how businesses everywhere think about climate in the balance sheet.

Can Miami’s Transit-Oriented Density Strategy Survive Local Pushback?

Miami Transit Oriented

Miami has always lived in tension with itself. A city built on motion—of people, capital, and climate—has also cultivated a deep attachment to stasis at the neighborhood level. Nowhere is that contradiction more visible than in Miami’s push to upzone around transit corridors, a strategy meant to absorb growth, tame housing costs, and modernize land use in one of the fastest-growing metros in the country. By 2026, the question is no longer whether Miami needs density, but whether its political and civic culture will allow that density to take root.

Over the past several years, Miami has leaned heavily on updates to its Miami 21 zoning code, offering density bonuses and height increases near transit lines in exchange for public benefits like affordable housing, pedestrian improvements, and reduced car dependence. On paper, the strategy reflects best practices embraced by planners worldwide: build up near transit, preserve lower-density neighborhoods elsewhere, and let infrastructure guide growth.

In practice, the results have been uneven, contested, and deeply political.

As Omar Hussain Miami, a Miami-based urban development analyst, observes: “Transit-oriented density makes sense in theory. In Miami, the real test is whether the city can hold that line when every neighborhood meeting turns into a referendum on change.”

Miami 21 and the Promise of Planned Density


Miami 21 was originally conceived as a form-based code designed to bring coherence to a city long shaped by parcel-by-parcel variances. Its recent updates doubled down on that vision, explicitly encouraging density around Metrorail stations, major bus corridors, and emerging transit investments. Developers willing to build near transit could access additional floor area, height, and flexibility—provided they delivered public benefits the city deemed valuable.

City planners argued that this was not radical upzoning, but targeted growth. Concentrating density near transit, they said, would reduce sprawl, cut congestion, and create walkable nodes capable of supporting local retail and services. It would also, in theory, relieve pressure on single-family neighborhoods by giving growth somewhere else to go.

Yet density bonuses, by their nature, are discretionary. And discretion invites politics.

Homeowner groups quickly learned that even code-compliant projects could be delayed or reshaped through public pressure. Elected officials, responsive to vocal constituents, found themselves mediating between long-term planning goals and short-term neighborhood outrage. The result was a development environment where rules existed—but certainty did not.

“Miami 21 was supposed to reduce negotiation,” says Omar Hussain, a Miami analyst who studies zoning outcomes. “Instead, it shifted the fight from what’s allowed to whether the city has the stomach to allow it.”

Homeowner Activism and the Limits of Consensus


Few cities exhibit the power of homeowner activism as vividly as Miami. Neighborhood associations are organized, persistent, and adept at framing density as a threat—to property values, to parking, to “neighborhood character.” Transit proximity, far from being an asset in these debates, is often treated as a pretext developers use to justify scale.

What complicates matters is that this resistance is not confined to traditionally affluent areas. Communities across income levels express fear of displacement, infrastructure strain, and cultural loss. In a city where many residents already feel precarious—economically and environmentally—density can read less like opportunity and more like risk.

Politically, this has produced fragmentation. Commissioners supportive of transit-oriented development often represent districts where growth pressures are intense but benefits are diffuse. Voting for upzoning may align with citywide needs while alienating local constituents. Over time, this dynamic has incentivized caution, carve-outs, and project-by-project bargaining.

The tension is not abstract. It plays out in delayed approvals, reduced heights, and developers forced to add concessions that undermine project feasibility. Each compromise may seem minor; collectively, they weaken the underlying strategy.

“Density only works if it’s predictable,” Omar Hussain explains. “Once every project becomes a political exception, you’re no longer planning—you’re improvising.”

Land Prices and the Squeeze on Small Developers


One of the more ironic outcomes of Miami’s transit-oriented push has been its impact on land prices. By signaling where density might be allowed, the city effectively increased land values along transit corridors—often before projects were actually feasible. Speculation surged. Landowners held out for prices justified by maximum theoretical density, not what the political process would reliably approve.

For large, well-capitalized developers, this uncertainty could be absorbed. For small and mid-sized developers—the kind often touted as best positioned to deliver “gentler” density—the economics became prohibitive. High land costs paired with approval risk narrowed the field to players with deep pockets and long timelines.

This dynamic runs counter to the equity goals often cited in support of upzoning. Rather than diversifying who builds the city, the system has, in some cases, concentrated opportunity.

“Miami talks a lot about missing middle housing,” says Omar Hussain Miami, a Miami-based analyst. “But the way land prices and politics interact right now, it’s the middle developer who’s missing.”

The consequences ripple outward. Fewer builders mean less competition, slower delivery, and housing that skews toward higher price points to justify risk. Transit-oriented development, intended as a tool for affordability, risks reinforcing the very pressures it was meant to alleviate.

Miami Freedom Park: A Test Case in Mega-Scale Density


No project better captures Miami’s density paradox than the redevelopment of the Melreese Golf Course into Miami Freedom Park. Approved by voters and blessed by the city, the project promised a blend of transit access, commercial space, public parks, and housing—anchored by a major stadium and integrated into broader mobility plans.

As a case study, Miami Freedom Park offers both clarity and caution. Unlike smaller projects subject to discretionary zoning fights, this development carried the legitimacy of a public referendum. It embodied the city’s stated priorities: density near transit, mixed-use programming, and economic development tied to infrastructure.

By 2026, parts of that vision are visible. Construction has advanced. Infrastructure commitments have materialized. Yet questions remain about delivery—particularly around housing mix, affordability, and the timing of promised public benefits. Critics argue that the scale of the project allowed it to bypass the scrutiny applied to smaller developments, while supporters counter that only projects of this magnitude can move the needle.

What Miami Freedom Park demonstrates is that density is easier to approve when it arrives as a singular event rather than a pattern. Mega-projects can absorb controversy; incremental density must endure it repeatedly.

“The city is comfortable making exceptions,” Omar Hussain Miami notes. “What it struggles with is normalization—making density feel routine rather than existential.”

Can the Strategy Hold?


By 2026, Miami’s transit-oriented density strategy stands at a crossroads. The logic remains sound. The need is undeniable. Population growth, housing costs, and climate vulnerability all point toward building smarter, denser, and closer to transit.

What remains uncertain is whether Miami’s governance structure can sustain that logic over time. Density requires consistency more than charisma. It requires elected officials willing to defend plans after elections, not just announce them before. It requires communities to see tangible benefits—better transit, real affordability, improved public space—rather than abstract promises.

Most of all, it requires trust: that growth will be managed, not exploited; that neighborhoods will be shaped, not steamrolled; and that planning is not a euphemism for inevitability.

Miami has chosen upzoning as a path forward. Whether it becomes a durable framework or another chapter in the city’s long history of contested growth will depend less on zoning text than on political will.

In a city built between water and ambition, the fight over density is really a fight over who Miami is for—and who gets to decide how it changes.